- - -
- hours mins seconds
to get your checks by
Thursday, Nov. 19th
 0
You have no items in your shopping cart.
Estate Account Checks: Payee, Signature, Order of Payment and Records
Last updated: November 17, 2026
There is a great deal written about opening an estate account and almost nothing about using one. The executor's real question arrives later, at a kitchen table, with a bill in one hand and a check book in the other.
Quick Summary
Estate account checks are paid from the estate's own account, under its own taxpayer number, never from the deceased person's account and never from yours. The payee line, the signature block and the stub all follow fixed conventions, and the order in which claims get paid is set by statute rather than by who asks first.
- The estate needs its own taxpayer number before the account can open.
- Estate money stays separate from the representative's own money.
- Sign in a representative capacity, which is what keeps you off the item personally.
- Claims are paid in statutory classes, not first come first served.
- Paying out of order can be personal, especially ahead of a federal claim.
- The stub is the accounting record the court will eventually read.
Here is what belongs on the check itself, by the kind of payment you are making.
| Payment | Payee line | Memo or stub |
|---|---|---|
| A creditor's bill | The creditor as the invoice names them | Invoice number and the claim class |
| Professional fees | The firm, not the individual adviser | What the fee covers and the approval date |
| Your own reimbursement | Your name, personally | What you paid for, with the receipt filed |
| A distribution | The beneficiary as the will names them | Partial or final, and the share it represents |
None of this is legal advice, and probate is unusually local. Your state's probate code, the court supervising the estate and the attorney handling it decide what you must actually do, so take anything here to them before acting on it.
Estate account checks are ordinary items in an unusual name, so business checks can be printed in the estate's own name with a stub wide enough for the accounting entry.
What this guide covers
- Can you write checks on the deceased person's account?
- What do you need before the bank will open the account?
- How should the payee line read?
- How do you sign without becoming personally liable?
- In what order must claims be paid?
- What should the memo line and stub record?
- When is it safe to pay the beneficiaries?
Can you write checks on the deceased person's account?
No. That account belongs to the estate now, and the bank will normally freeze it the moment it learns of the death. Letters appointing you do not give you signing authority on it, and a power of attorney does not survive the person who granted it.
What you get instead is control of the estate as a whole. One state puts the position plainly: the personal representative has the management and control of the estate. That control is exercised through a new account opened in the estate's name.
This is the single most common early mistake. Families pay a funeral bill from the deceased person's account because the card still works, and the entry becomes very hard to explain later.
What do you need before the bank will open the account?
A taxpayer number for the estate, your appointment papers and a death certificate. The estate is a separate taxpayer, and federal guidance for executors tells you to apply for an employer identification number for the estate.
That requirement is not just guidance. The Treasury regulations on identifying numbers require that an estate obtain an employer identification number, which is why no bank will take your own number instead.
- Get the number first, because the account cannot open without it.
- Take your letters of appointment in the form the court issued them.
- Open the account in the estate's name, not in yours with a label.
- Order stock in that exact name, matching the account title.
- Record the date of death balance for every account you find, in writing.
Why must estate money stay separate?
Because you are a fiduciary, and the standard is borrowed from trust law. One state provides that a personal representative is a fiduciary who shall observe the standards of care applicable to trustees, and the trustee rule in the same code requires a trustee to keep trust property separate from the trustee's own property.
Put those two sentences together and commingling is not untidiness. It is a breach of the duty you were appointed under, and it is the finding that costs executors money.
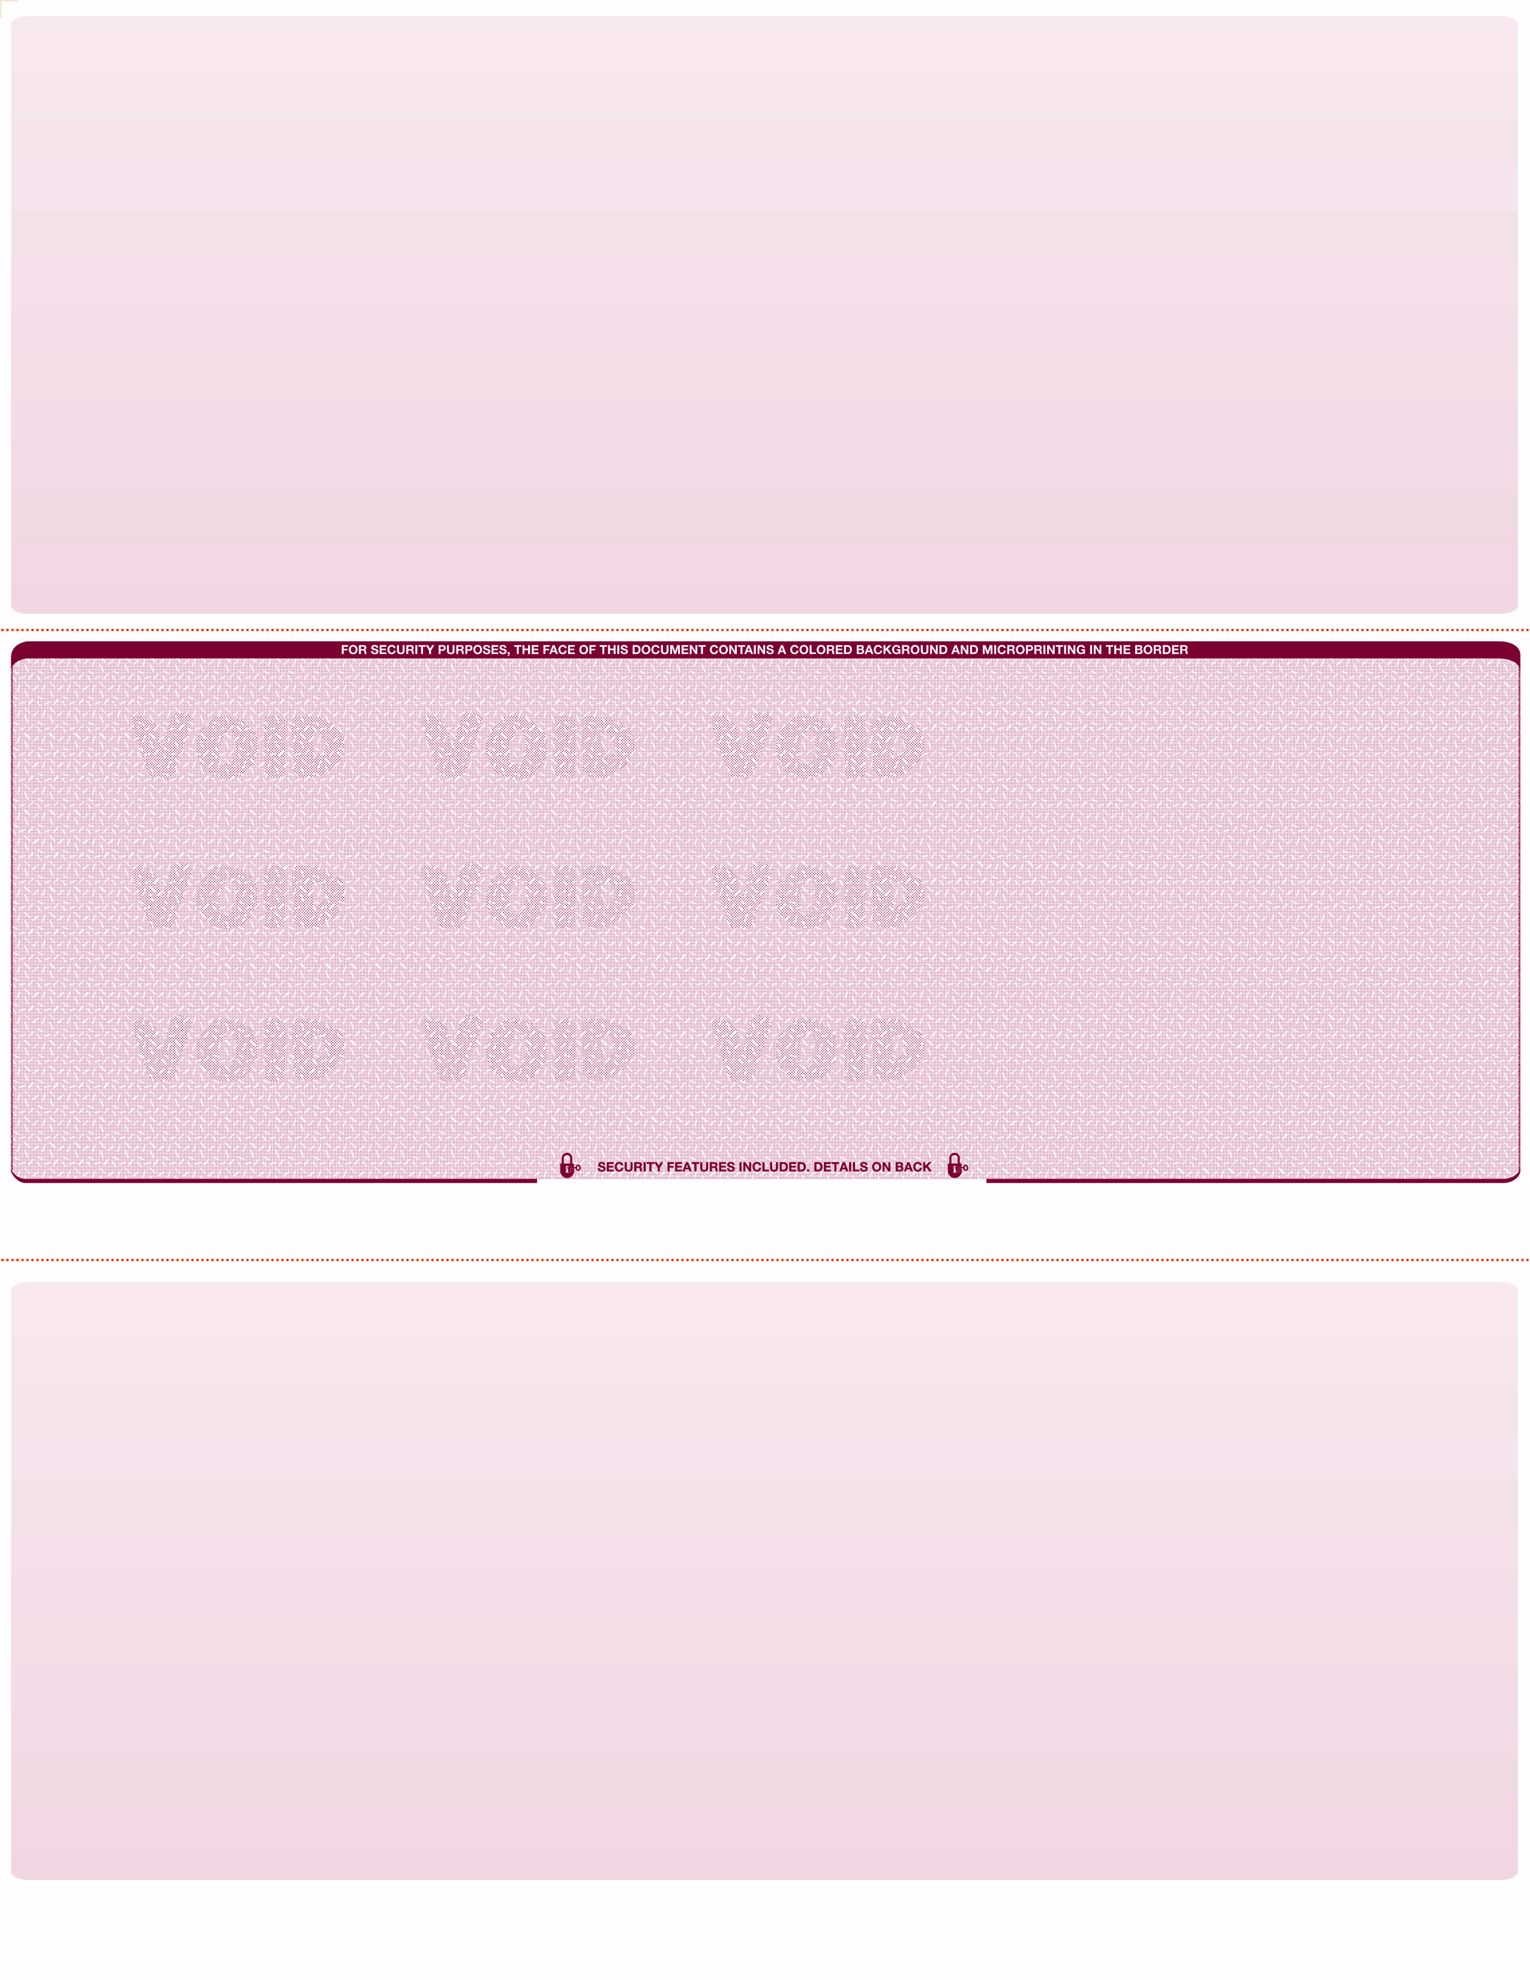
Two record areas suit an estate, because every payment needs an accounting entry. See blank checks on the middle for that layout.
How should the payee line read?
On a check you write, name the payee exactly as the invoice or the will names them. The harder question is the reverse one: what should a check coming in to the estate say, and that is where banks argue with each other.
The commercial code settles the principle. Where an instrument is payable to a representative, the instrument is payable to the trustee, the representative, or a successor of either. So a check made out to the estate is legally payable to you in your appointed role.
Banks still have house rules. Some will only issue a check naming the representative alongside the estate, and the estate's own bank may then query it. If you are asking a payer for a check, agree the exact wording with your bank first and give the payer that wording in writing.
What if a check arrives payable to the deceased person?
It still belongs to the estate, and it goes into the estate account rather than anywhere else. For a government check there is even prescribed wording. The federal regulation on checks issued to deceased payees gives the endorsement form as the payee's name by the representative's name, naming their role and the estate.
How do you sign without becoming personally liable?
By showing your capacity on the item, every single time. The commercial code provides that where a representative signs on behalf of the represented person and the signature shows that it was made in a representative capacity, the representative is not liable on the instrument.
In practice that means the signature line carries your name and your role, and the account is already in the estate's name above it. Signing your bare name on an estate check is the habit worth breaking today.
- Print the estate's name on the face of the stock.
- Sign your name followed by your role, not your name alone.
- Use the same wording every time, so the file reads consistently.
- Never pre sign blank items for somebody else to complete.
How many signatures should an estate account need?
One, in most cases, because a single personal representative was appointed. Where two people were appointed together, the bank mandate should say whether both must sign.
Settle that question when the account opens rather than later. Co representatives who discover mid administration that they cannot pay a bill without meeting in person tend to start cutting corners, and that is how an estate account check ends up signed by one person who was not authorized to sign alone.
In what order must claims be paid?
In statutory classes. Every state sets an order, and it is not the order the bills arrived in. One state's code requires that the personal representative shall make payment in the following order of priority, then lists the classes.
Two further rules make the order bite. California provides that no debt of any class may be paid until all those of prior classes are paid in full. Virginia adds that no preference shall be given in the payment of any claim over any other claim of the same class.
| Typical position | What sits there |
|---|---|
| Earliest | Administration costs, then funeral expenses within limits |
| Early | Debts and taxes with a preference under federal law |
| Middle | Certain medical expenses of the last illness, and family allowances |
| Later | State taxes, then judgments and secured claims as the statute directs |
| Last | All remaining general claims |
Read that as a shape, not as your state's list. The classes and their contents differ, and the order is one of the few things in probate that is worth looking up rather than remembering.
What happens if you pay out of order?
You can end up paying twice, once from the estate and once from yourself. The federal priority statute provides that a representative who pays other debts before a claim of the Government is liable to the extent of the payment for unpaid claims of the Government.
Federal guidance for executors says the same thing in plainer words for an insolvent estate, noting that the extent of such personal responsibility is the amount of any other payments made. If an estate looks short, stop writing checks and take advice.
What should the memo line and stub record?
Enough for the final accounting, which is a document you will have to produce whether you expect to or not. The memo line is not where the legal work happens, but the stub is where your evidence lives.
- What the payment was for, in words a stranger would follow.
- The claim or invoice reference, and the class it falls in.
- The approval, including the court order where one was needed.
- Partial or final, for anything paid in stages.
- The running balance, so the account ties to the accounting.
Keep the canceled items too. A court reviewing a final account wants to see what was actually paid and to whom, and a paid item is the cleanest proof of both.
A check at the head of the page leaves the record area underneath. See blank checks on the top for that layout.
Can you reimburse yourself from the estate?
Yes, for costs you genuinely advanced, and only against records. Executors front the funeral bill, the certified copies and the travel more often than anyone admits, and there is nothing wrong with recovering it.
What makes it defensible is the paperwork. Keep the receipt, write the reason on the stub, and pay yourself by a traceable item rather than by moving cash. Then the entry explains itself if a beneficiary ever asks.
When is it safe to pay the beneficiaries?
Once the creditor window has closed and the higher classes are settled, and not before. This is the hardest part of the job, because the family's patience usually runs out well ahead of the statutory timetable.
- Wait for the claim period to end, as your state defines it.
- Settle taxes and administration costs first, in their statutory order.
- Hold a reserve for the final return and the closing costs.
- Consider a partial distribution rather than a full one, if pressure is mounting.
- Get a signed receipt from every beneficiary for every payment.
Mark each item partial or final on the stub. A beneficiary who cashes a payment marked final has been told something important, and a file that records it protects everybody.
Related reading
- Check register covers the running record a final accounting draws on.
- How to write a business check by hand covers getting the payee line right.
- How long to keep business checks covers retaining the paid items.
- How to endorse a check covers signing an item received in a representative role.
What to do next
Before you write anything from the estate account, look up your own state's order of payment and write the classes on one sheet kept with the check book. That sheet is the difference between an orderly administration and a personal liability.
Then order stock in the estate's exact name. Business checks are printed to the account title you supply, and blank check stock suits an estate being administered through accounting software.
About the Author
Executors are the most careful customers we deal with, and the most anxious. They almost always ask the same thing, which is whether the name can be printed exactly as the court wrote it. The answer is yes, and it is worth getting right, because that printed line is the first thing a bank reads.
The points above on taxpayer numbers, fiduciary standards, order of payment, representative signatures and government check endorsement are drawn from federal tax guidance, federal regulations, the commercial code and the probate codes of several states. They are illustrations. Your state and your court decide the rest.