- - -
- hours mins seconds
to get your checks by
Tuesday, Nov. 17th
 0
You have no items in your shopping cart.
Booster Club Checks: Controls, Records and the Private Benefit Trap
Last updated: November 13, 2026
Booster club money is handled by parents who did not ask for an accounting job, in evenings, between matches. The remarkable thing is how well it usually goes. The problems, when they come, almost always trace to the same three places.
Quick Summary
A booster club needs three things working: two people involved in every payment, a written trail from event cash to the bank, and a handover that counts what is being passed on. Behind all of it sits a rule worth knowing, which is that no part of the net earnings of a section 501(c)(3) organization may inure to the benefit of any private shareholder.
- Two signatures above a set amount, written into your rules.
- Never the same person preparing, signing and reconciling.
- Count event cash on site, two people, one signed sheet.
- Bank takings intact, without paying expenses from the tin.
- Reimburse against receipts, approved by someone other than the claimant.
- Individual credit accounts draw scrutiny, because of the inurement rule.
The three failure points below account for almost everything that goes wrong in a volunteer run group.
| Where it goes wrong | What it looks like | The fix |
|---|---|---|
| Event cash | A tin counted later, by one person, at home | Two counters, a signed sheet, banked intact |
| One willing volunteer | The same person does everything for years | Split the three roles, even if it is slower |
| Handover | A box of papers and an unchanged signatory list | A counted list both people sign |
| Individual accounts | Fundraising credited to one family's fees | Take advice before operating that way |
Background on handling money in a volunteer group, not legal or tax advice. What applies to your club depends on its exemption status, its governing documents and your school district's rules, so check those and ask your own advisers.
On the payment side, business checks can be printed with two signature lines, which makes the control visible on every item.
What this guide covers
- Who should sign the checks?
- How should event cash be handled?
- How should volunteers be reimbursed?
- What is the private benefit problem?
- What records should the treasurer keep?
- What should happen at handover?
- How should the account itself be set up?
Who should sign the checks?
Two officers above an amount the committee agrees, and never the same person who prepared the payment and reconciles the account. The reason is not suspicion. It is that a volunteer handling money alone has no way to prove they did it properly, and that exposure is unfair to them.
- Set the two signature threshold in writing, at a figure that fits your spending.
- Name three signatories, so holidays do not stall payments.
- Keep the stock away from the signer, in a different household if practical.
- Have a second officer read the statement each month and initial it.
Say out loud why you are doing it. A committee that explains these controls as protection for the volunteers, rather than as distrust, gets them adopted without anyone taking offense.
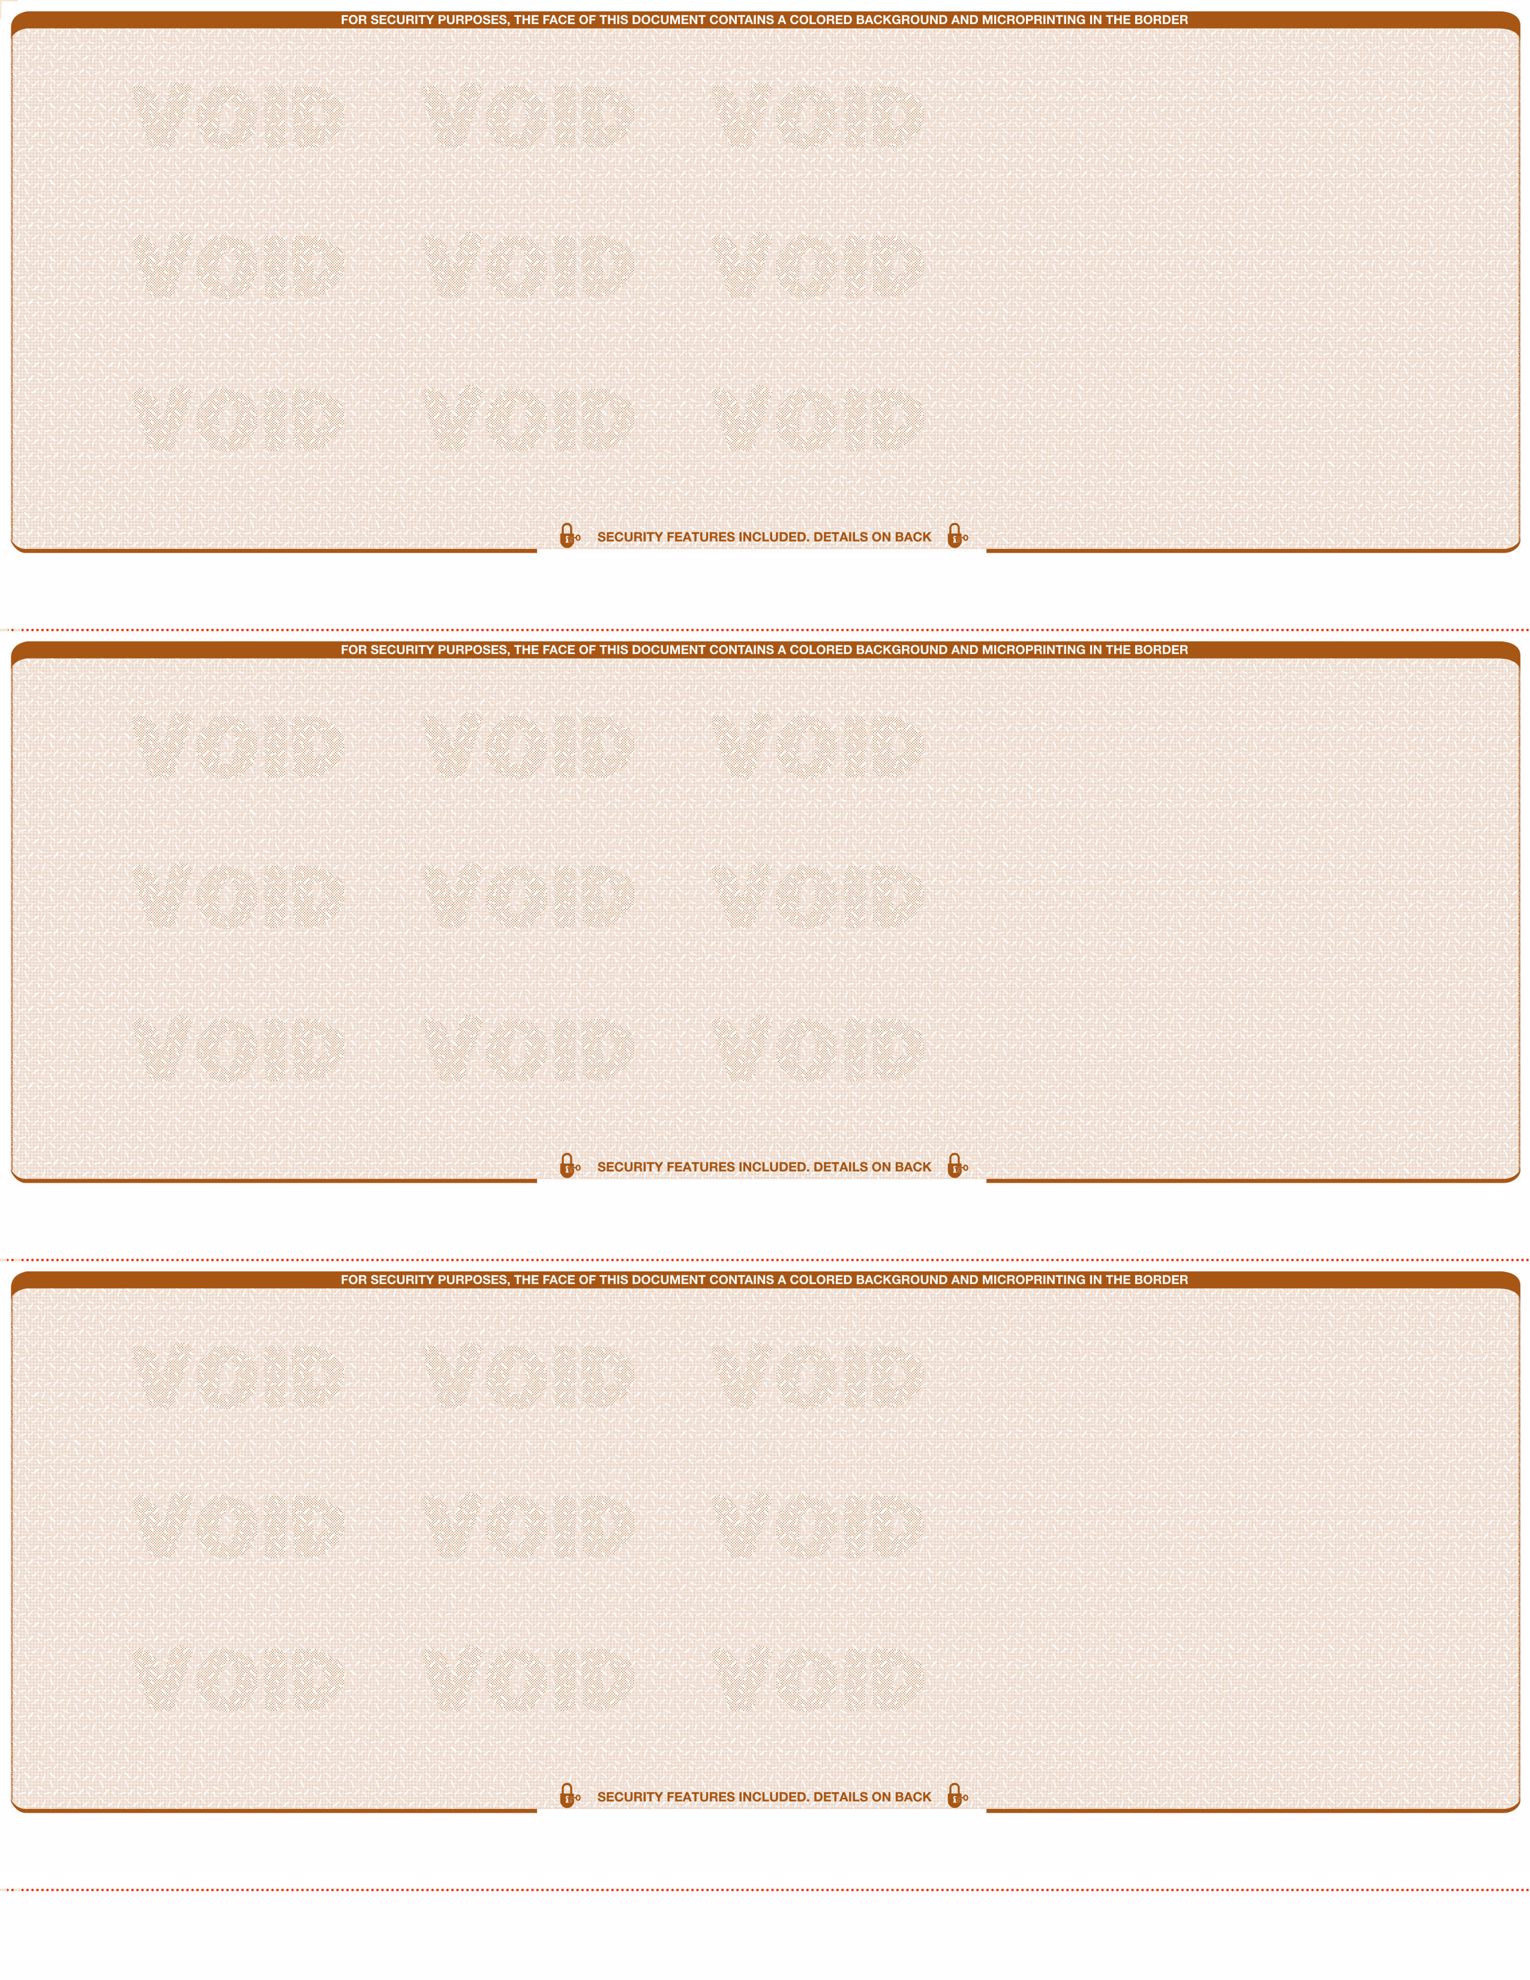
A small group rarely needs continuous stationery. See blank checks three per page for a practical format.
How should event cash be handled?
Counted where it was collected, by two people, before anyone goes home. Almost every booster club shortfall starts with a tin that travelled in a car and was counted the next morning by whoever had it.
- Start with a recorded float so you know what was there before trading.
- Count on site with two people, and write the total on one sheet.
- Both sign the sheet, including the float figure and the net takings.
- Bank it intact, without paying anybody out of the takings.
- Match the deposit to the sheet when the statement arrives.
Paying a supplier from the tin is the common mistake. It is well meant and it destroys the trail, because the deposit no longer matches anything and the expense has no record.
How should volunteers be reimbursed?
Against a receipt, on a short claim form, approved by somebody who is not the claimant, and paid by check. Keep the form to four lines so people actually fill it in.
- What was bought and for which event or team.
- The amount, matching the attached receipt.
- Who is being repaid and the date.
- The approver's signature, which is never the claimant's own.
Pay quickly. A parent who waited two months for forty dollars does not complain, they simply stop offering to help, and a volunteer group cannot afford to lose people that way.
What is the private benefit problem?
It is the rule that sits behind the most common booster club practice, which is crediting fundraising to the family who did it. Federal guidance states that no part of the net earnings of a section 501(c)(3) organization may inure to the benefit of any private shareholder.
The guidance defines that term broadly. A private shareholder or individual is described as a person having a personal and private interest in the activities, with examples of private interests including the creator or the creator's family and shareholders of the organization.
This is not a reason to panic. It is a reason to take advice before running individual credit accounts, and to be able to explain how your group decides who benefits from money it raises collectively.
What does a safer arrangement look like?
- Raise and spend for the group, not for named participants.
- Set assistance by need, on criteria the committee approved in advance.
- Minute the decision, including who was excluded from the vote.
- Keep participation open, so helping is not a condition of benefit.
What records should the treasurer keep?
Five sets, and none of them are difficult. They are simply the things nobody has when a question is asked two years later.
- The register, with every item in number order including voids.
- Bank statements, read monthly by a second officer.
- Invoices and receipts, matched to the payment that settled them.
- Minutes approving spending, particularly anything unusual.
- Event cash sheets, signed by both counters.
Our guide to the check register covers the first of those, which is the document a new treasurer most needs.
Two record areas suit a group that files one copy and gives one to the committee. See blank checks on the middle for that layout.
What should happen at handover?
A counted, written exchange rather than a box handed across at the end of a meeting. Handover is the weakest point in any role that changes every year, and it is the easiest one to fix.
- Count the unused check stock and write down the next number.
- List outstanding items with their ages.
- Print the last reconciliation and attach the statement.
- Change the bank signatories on the day, not eventually.
- Both people sign the list, and the committee keeps a copy.
This protects the person leaving. A signed list showing everything was in order on the day they stepped back is worth having if anyone ever asks a question about a period they are no longer responsible for.
How should the account itself be set up?
Before any of the controls above can work, the group has to know what it legally is. A surprising number of booster clubs operate for years without anyone being certain, which makes every later question harder to answer.
| Question | Why it decides things |
|---|---|
| Are we a separate organization? | Decides whose account the money sits in |
| Do we hold our own exemption? | Decides which rules apply to what we raise |
| Does the district have rules for us? | Often sets approvals, accounts and reporting |
| Who is named on the bank mandate? | Decides who can actually move money today |
| Where are the governing documents? | Settles most arguments before they start |
What if nobody knows the answers?
Find them this season rather than next. Ask the school office, ask the bank who is on the mandate, and search for the organization's registration. None of it takes long, and the group that knows what it is can answer a parent's question in one sentence instead of three meetings.
Write what you learn into a single page and keep it with the check book. The next treasurer will inherit the answers instead of starting the search again.
Should the club have its own stock, or use the school's?
Its own, where the club is a separate organization with its own account. Paying club expenses from a school account, or the reverse, mixes two sets of money and two sets of rules, and it is the thing an auditor unpicks most slowly.
Order stock in the organization's registered name rather than in the name of the team or the season. Teams get renamed and seasons end, and a check book that outlives either is still perfectly usable.
Related reading
- Check register covers the record a volunteer treasurer hands on.
- Check signing policy covers limits and who may sign.
- How to write a business check by hand covers a payment written at a table rather than printed.
- Blank check security features explains the features printed into the paper.
What to do next
At your next committee meeting, agree the two signature threshold and write it in the minutes. Then put a cash count sheet in the box that goes to every event, because that one piece of paper prevents most of the trouble described here.
Then order stock that matches how you work. Business checks can carry two signature lines, and blank checks three per page suit a group writing a handful of payments a month.
About the Author
Orders from parent groups arrive in two waves, September and June, which tells you most of what you need to know about the job. One when the season starts, and one when a new treasurer takes over and cannot find the old book.
The private benefit point here follows federal guidance on inurement for charitable organizations. Your group's exemption status, governing documents and school district rules decide what applies, so take advice before changing how you credit fundraising.