- - -
- hours mins seconds
to get your checks by
Tomorrow, Nov. 3rd
 0
You have no items in your shopping cart.
1099 Vendor Payments and the Checks You Write
Last updated: November 2, 2026
Nobody enjoys January. The part that turns it from admin into a week of detective work is almost always the same: 1099 vendor payments that were written as checks, with no record of what each one was for.
Quick Summary
Paying a vendor by check does not change your reporting duty, and for 2026 the reporting threshold moved. The IRS instructions for the 2026 forms tell filers to report nonemployee compensation of 2,000 dollars or more, and that figure may be adjusted for inflation from 2027.
- The method does not matter. A check, a transfer or a card payment all count toward the same total.
- The threshold moved for 2026. Nonemployee compensation is reported at 2,000 dollars or more under the current instructions.
- Indexing starts after that. The instructions note the figure may be adjusted for inflation beginning in calendar year 2027.
- One date governs. Form 1099-NEC is due on or before January 31, and so is the recipient's copy.
- No W-9, no clean payment. Where a taxpayer identification number has not been furnished, backup withholding applies.
- Your register is the source document. If the purpose was never recorded, the total has to be rebuilt by hand.
These are the thresholds and dates the 2026 instructions set out, with the form each one belongs to.
| What you paid | Form | Threshold in the 2026 instructions |
|---|---|---|
| Nonemployee compensation | 1099-NEC, box 1 | 2,000 dollars or more |
| Rent | 1099-MISC | Grouped at the 2,000 dollar level |
| Medical and health care payments | 1099-MISC | Grouped at the 2,000 dollar level |
| Gross proceeds paid to an attorney | 1099-MISC, box 10 | At least 600 dollars |
| Royalties | 1099-MISC, box 2 | At least 10 dollars |
What follows is general information about information reporting and record keeping. It is not tax or legal advice, thresholds and boxes change from year to year, and your own facts decide what is reportable, so confirm the detail with your accountant before you file.
The record side is where this gets easy or painful. Business checks with a voucher stub capture the purpose at the moment the payment is written, which is the only moment it is cheap to capture.
What this guide covers
- What changed for 2026 payments?
- Which check payments end up on a 1099?
- Do you need a W-9 before you pay?
- What if a vendor never returns one?
- When are the forms due?
- How do your check records feed the totals?
- What should you do before year end?
What changed for 2026 payments?
The reporting threshold moved up. The IRS instructions covering the 2026 forms direct filers to enter nonemployee compensation of 2,000 dollars or more, and the What's New section states that for tax years beginning after 2025 the minimum threshold for reporting certain payments increased to that amount, with inflation adjustment possible from calendar year 2027.
That matters more than it sounds. Plenty of guidance still circulating online quotes the older figure, so a business following last year's checklist will prepare forms it no longer has to file, and will not know which of the two numbers its software used.
One caution worth holding onto. A higher threshold removes a filing duty, not a record keeping one. The payment still has to be booked correctly, and a vendor who crosses the line next year will need a total that was tracked all along.
Which check payments end up on a 1099?
Reporting follows what the payment was for, not how it left your account. A check to a contractor for services is nonemployee compensation on the 1099-NEC. Rent to a landlord, medical and health care payments, royalties and legal gross proceeds sit on the 1099-MISC, each in its own box with its own threshold.
The practical trouble is mixed payments, which checks encourage. One check often settles a fee plus materials plus a reimbursed expense, and only part of that belongs in the reported figure.
- Split mixed payments in the record, even when the check is written for the combined amount.
- Keep reimbursements identifiable rather than folded into a service total.
- Record goods separately from labor where an invoice covers both.
- Note the entity type when you set the vendor up, because it decides whether anything is reportable at all.
A format with room to write beats one without. Our computer checks range includes voucher layouts where the stub carries that detail, and types of business checks compares the formats side by side.
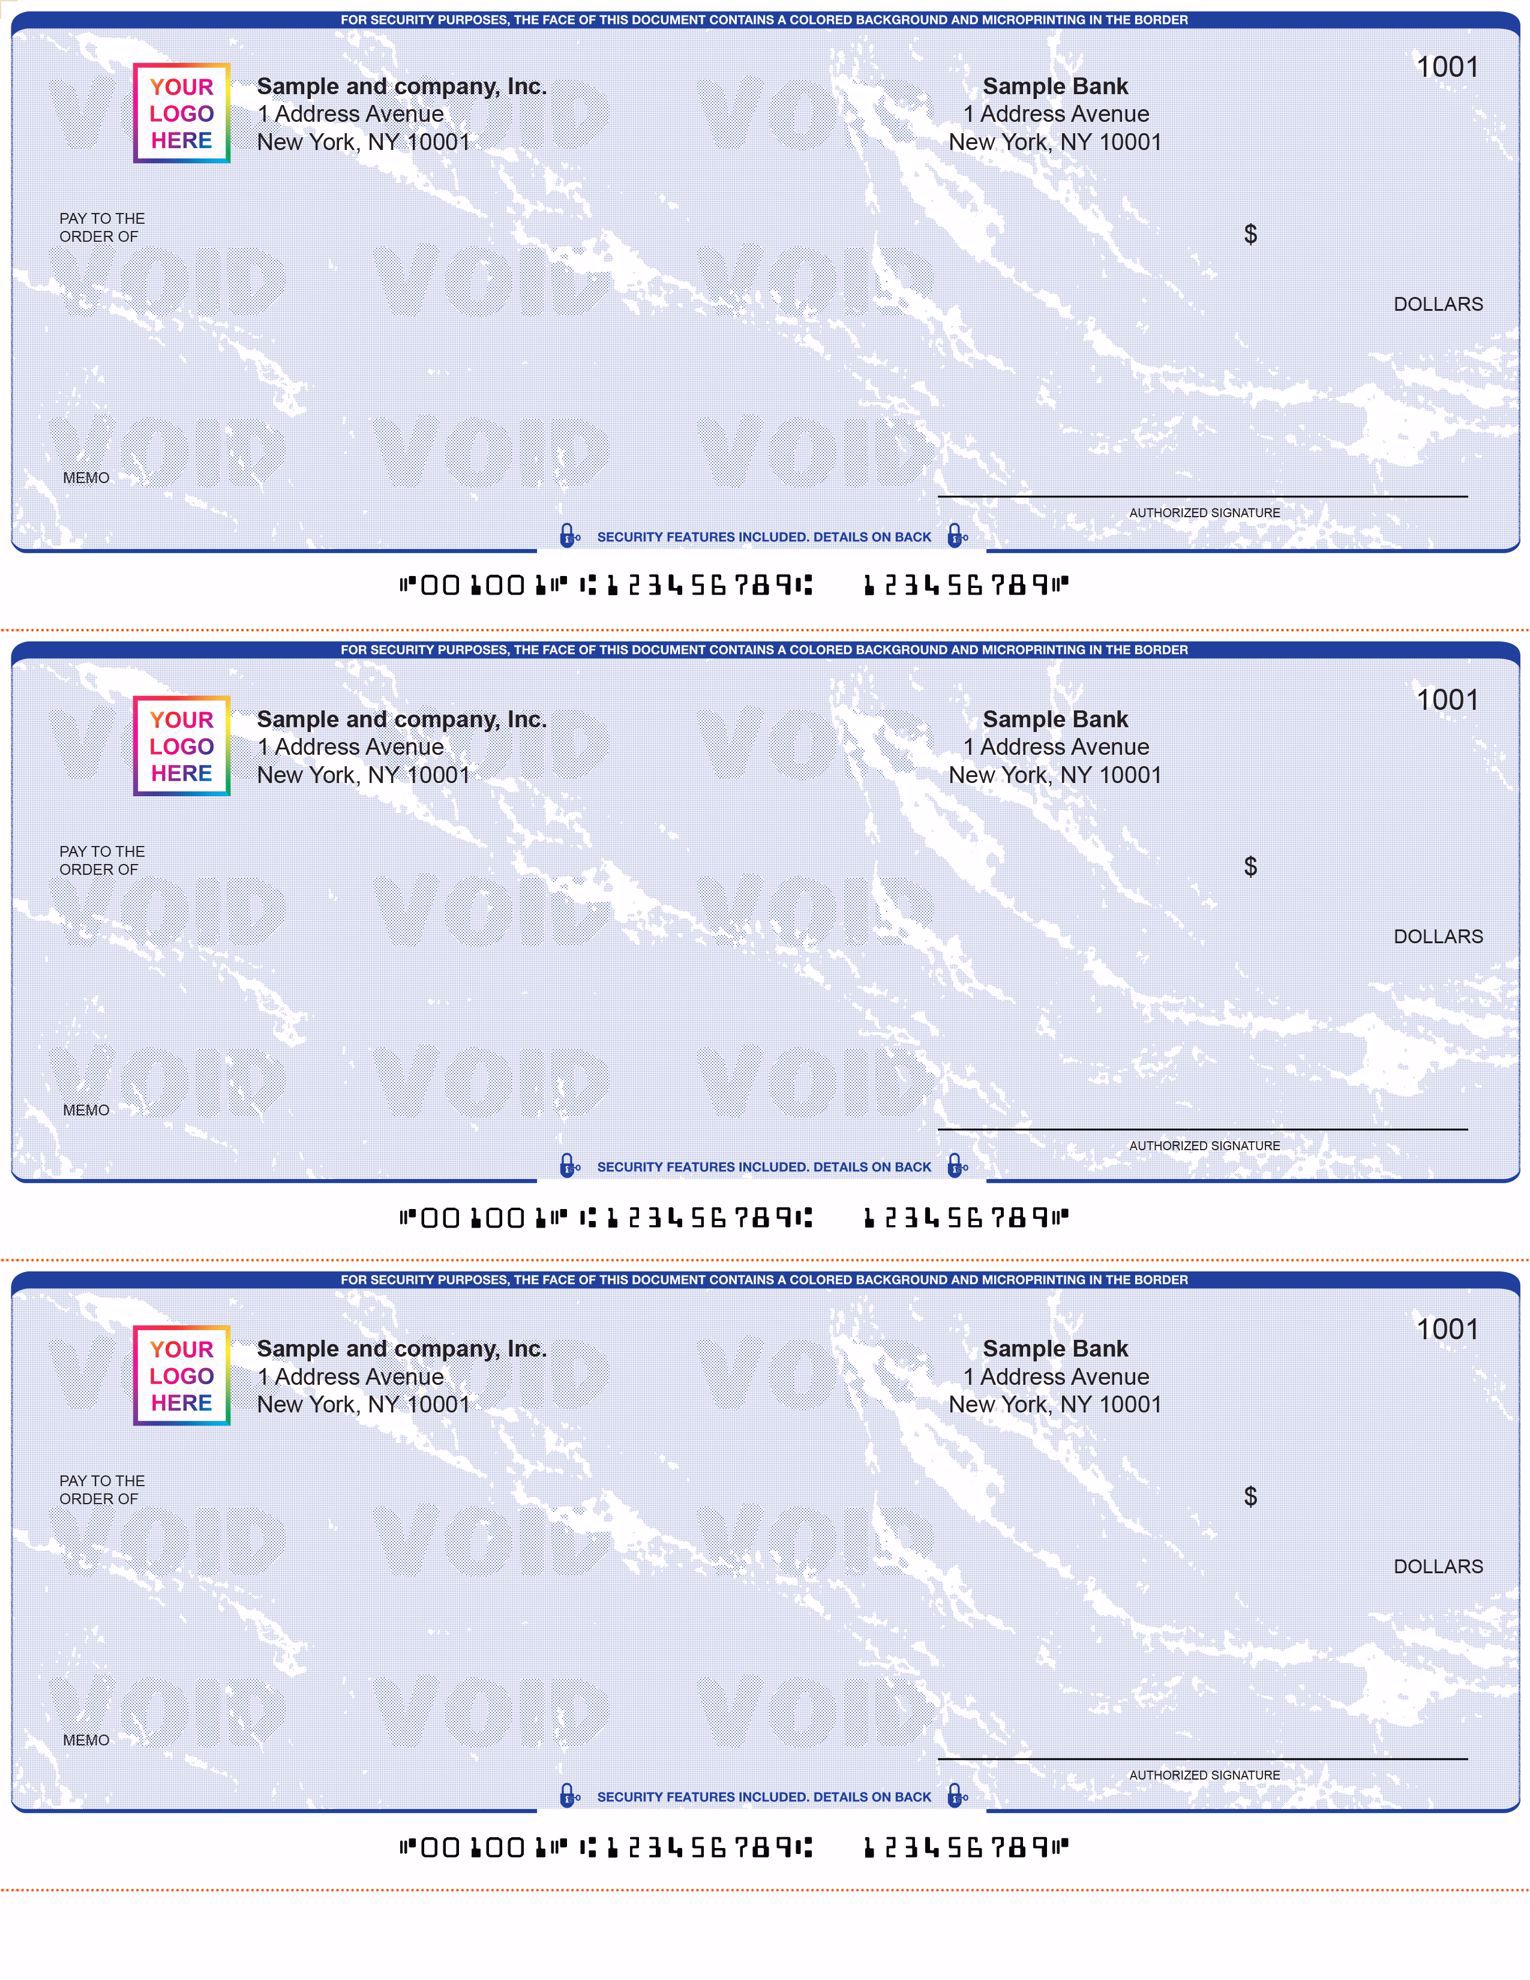
For a December run with many small vendor payments, a three to a page format moves faster. See business checks 3 on a page for that layout.
Do you need a W-9 before you pay?
Ask for it before the first check leaves. Form W-9 is how a payee gives a correct taxpayer identification number to the person who will have to file an information return, and the IRS describes it exactly that way.
The reason to front-load it is leverage. Before you pay, the form is one more item on a short list. After you pay, you are asking a busy contractor for paperwork that benefits you and not them, which is how a January deadline turns into a series of unanswered emails.
- Request it with the first paperwork, alongside insurance and bank details.
- Check the name against the entity, not against the invoice letterhead.
- File it where payments are processed, not in a personal inbox.
- Refresh it when something changes, such as a new entity or a change of name.
What if a vendor never returns one?
Then backup withholding is the answer, not a shrug. The IRS instructions state that persons who have not furnished their taxpayer identification numbers are subject to withholding on the relevant payments, with the rate set out in the IRS backup withholding material rather than in the form instructions.
In plain terms, you keep part of the payment back and send it on to the IRS instead of to the vendor. Telling a vendor that in advance tends to produce the W-9 faster than any reminder email, and it is a far better conversation to have before the check is written than after.
When are the forms due?
January 31. The instructions cite section 6071(c) for filing Form 1099-NEC on or before that date, and the statement to the recipient is due by the same day, which means there is no quiet window between sending copies out and filing.
Work backwards from it and the real deadline is in December. Every W-9 you do not have, every payee name you cannot match and every check whose purpose nobody recorded becomes a task competing with the same single date.
How do your check records feed the totals?
Three fields decide whether reporting is an export or an investigation: who you paid, how much, and what for. Electronic payments carry the first two automatically. A check carries them only if someone wrote them down.
| What reporting needs | Where it comes from on a check | What goes wrong without it |
|---|---|---|
| The right payee | The payee line, written as the entity is registered | A name mismatch notice, and a vendor who disputes the form |
| The annual total | The register, read as a full year rather than a month | A vendor slips under or over the line unnoticed |
| The purpose | The voucher stub, or the memo line at a minimum | Services and materials get reported as one number |
| Proof it was paid | The issued number and the statement entry | A disputed payment with nothing to point at |
A check register is the second row of that table, and how to write a business check by hand deals with the payee line itself, where the registered name has to appear exactly as filed.
What should you do before year end?
Six jobs, none of which take long in November and all of which take hours in late January. Doing them now is the difference between a quiet month and a scramble.
- Pull a vendor list by annual total, not by month, so the borderline cases are visible.
- Chase every missing W-9 while you still have payments to make.
- Check payee names against the W-9 rather than the invoice.
- Split the mixed payments in your books before the totals are frozen.
- Reconcile the check sequence, so no issued payment is missing from the year.
- Confirm which threshold your software used, given the change for 2026 payments.
If the forms go out by mail alongside a final check run, the envelopes matter more than you would think. Double window envelopes keep the address from being hand written on a deadline.
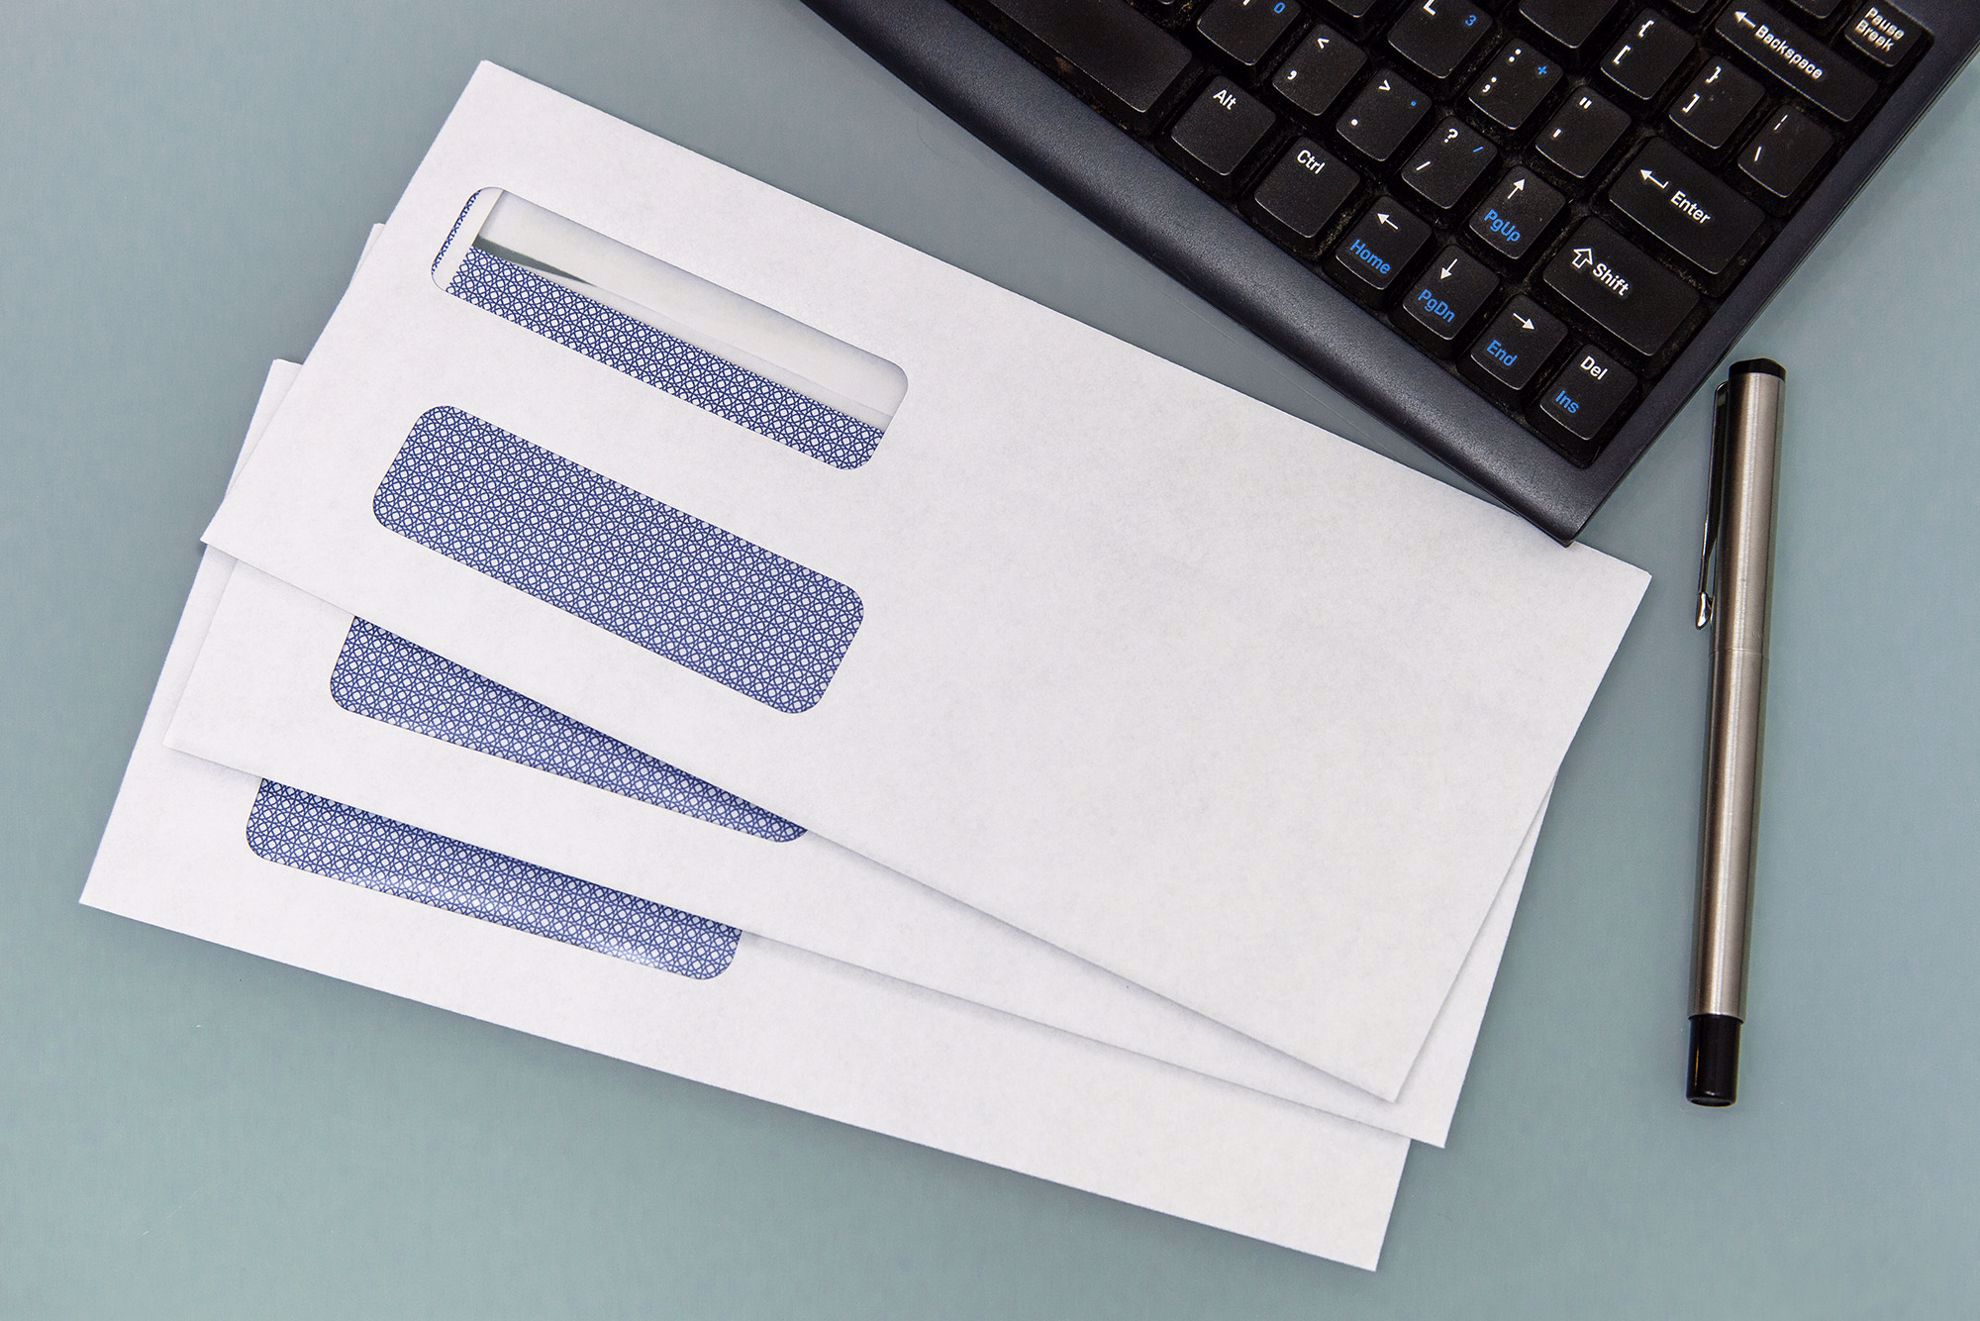
Sizing is covered in our guide to business check envelope size.
Related reading
- Check register covers logging each payment against its number.
- Types of business checks runs through each format and what the stub carries.
- What is a voided check covers handling a void so the year's sequence stays complete.
- High security business checks covers the stock used for larger vendor payments.
What to do next
Open your register and sort this year's payments by vendor total. The names near the threshold are your December work, and the ones with no purpose recorded are the reason January usually hurts.
If the stock you are writing on has no room to record a purpose, that is worth fixing before the final run. Business checks are printed with the voucher layout and number range you specify, and an order approved before the cutoff is produced the same day.
About the Author
November and December are the busiest weeks of the year at Checks Next Day, and the orders tell you why: companies clearing vendor payments before the books close, almost always asking for a format with a bigger stub than the one they have been using.
The thresholds and dates on this page were taken from the current IRS instructions for the 1099 forms and from the IRS page describing Form W-9. Tax rules change each year and your own circumstances govern, so treat your accountant as the authority for your filing.